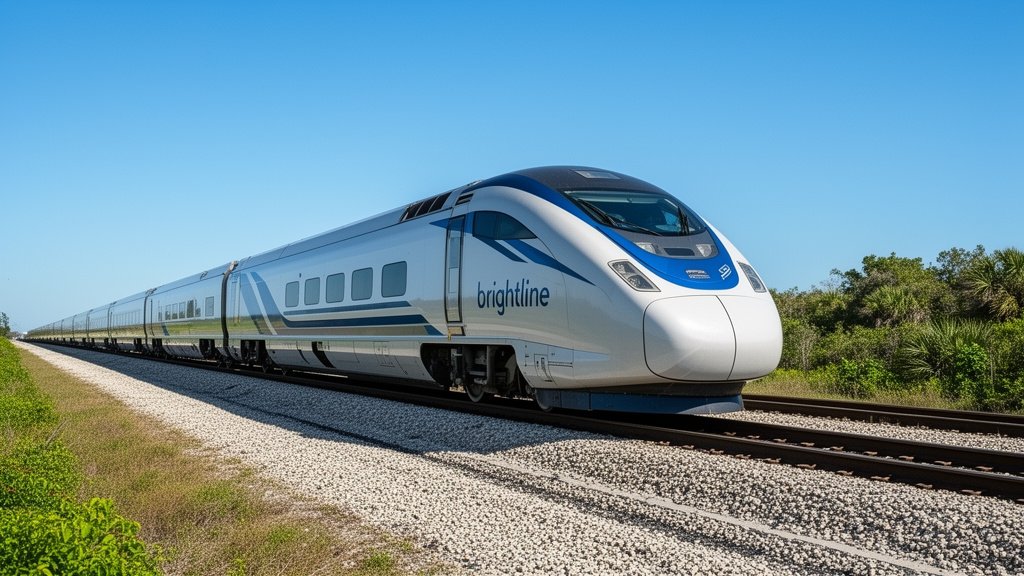
Brightline Shifts Gear: Strategic Restructuring Amid Bankruptcy Filing
Florida’s high-speed rail operator, Brightline, has officially moved to initiate a comprehensive financial restructuring process amidst a concurrent bankruptcy filing, marking a significant, transformative shift in the operational trajectory of private rail infrastructure. The strategic move, aimed at reorganizing billions in corporate debt, seeks to stabilize long-term operations for the premier high-speed rail network that connects South Florida’s major metropolitan hubs, including Miami and Orlando. By entering this process, the organization intends to address its existing capital structure, ensuring that it remains positioned to maintain service while navigating the complexities of large-scale infrastructure financing.
Key Highlights
- Brightline entities have officially entered into a court-supervised restructuring agreement to reorganize billions of dollars in corporate debt.
- The legal filing is strategically designed as a reorganization effort rather than a cessation of operations, emphasizing the company’s commitment to continued service.
- The restructuring process targets the stabilization of capital obligations, allowing the firm to realign its balance sheet with its long-term growth and expansion goals.
- Operations remain unaffected by the filing, with high-speed passenger service continuing across the Florida corridor as the financial restructuring proceeds.
The Strategic Realignment of Brightline Operations
The announcement that Brightline has moved to restructure its debt through a bankruptcy filing marks a critical juncture for what has been widely touted as the most ambitious private-sector rail project in the United States. For years, the company has operated under a unique financing model, relying heavily on Private Activity Bonds (PABs) and significant private equity to fund the massive upfront costs of rail infrastructure. This recent legal maneuver is, at its core, a mechanism for the company to shed the weight of its current debt load while maintaining the continuity of its core assets.
Understanding the Financial Restructuring Process
Financial restructuring in the context of major infrastructure projects is rarely a signal of project failure, but rather a surgical approach to capital management. By seeking this relief, Brightline is looking to renegotiate terms with its creditors, potentially extending maturities, adjusting interest rates, or converting portions of debt into equity stakes. This process is essential for companies dealing with the ‘lumpy’ nature of infrastructure investments—where capital expenditure is extremely front-loaded, but revenue generation from passenger volume scales more gradually over time.
Industry analysts note that this filing provides the legal breathing room necessary to align the company’s high-interest obligations with its current revenue generation performance. By working within the bankruptcy framework, Brightline aims to protect its physical assets—the tracks, the stations, and the rolling stock—from forced liquidation, effectively insulating the passenger experience from the internal financial engineering taking place at the corporate entity level.
Impact on Infrastructure and Expansion
One of the primary concerns for stakeholders and passengers alike is whether this restructuring will stifle the company’s expansion plans, specifically the anticipated growth beyond Florida. Historically, Brightline has positioned itself as the gold standard for high-speed rail, aiming to prove that private entities can succeed where public agencies often struggle with ballooning costs and bureaucratic delays.
Under this new reorganization plan, the company is expected to scrutinize its project portfolio. While the focus remains on stabilizing the Florida corridor, observers are watching closely to see if this pivot impacts timelines for further developments. The reorganization does not necessarily halt these future goals; rather, it makes them contingent on a leaner, more sustainable capital foundation. By cleaning up its balance sheet, Brightline is effectively ‘de-risking’ itself for potential future investors or government-backed loans that might require a more predictable debt-to-equity ratio.
Market Confidence and Regulatory Outlook
The move is also being viewed through the lens of regulatory scrutiny. The Federal Railroad Administration (FRA) and the Department of Transportation (DOT) have both played pivotal roles in supporting Brightline’s growth through loan programs and safety oversight. This bankruptcy filing creates a dynamic shift in how these agencies will view the project moving forward.
However, the consensus among transit experts is that the foundational premise of Brightline—providing rapid, car-alternative transit in high-density corridors—remains economically sound. The issue has never been demand; it has been the high cost of debt. If successful, this restructuring could prove that even a project with high entry barriers can survive by utilizing modern bankruptcy tools to calibrate its financial exposure. This could, ironically, establish a ‘blueprint’ for future private-public infrastructure initiatives that face similar debt-servicing challenges.
FAQ: People Also Ask
Q: Does this bankruptcy filing mean the trains will stop running?
A: No. Brightline has explicitly stated that this is a financial restructuring of its corporate debt. Operational service on the current Florida rail lines will continue as scheduled throughout the process.
Q: Is Brightline now a public or government-owned entity?
A: No. Brightline remains a private company. The restructuring is a private, court-supervised process intended to reorganize debt, not a nationalization of the service by the government.
Q: Will this change the price of tickets or services?
A: There is no immediate indication that the restructuring will lead to direct price hikes. The process focuses on corporate-level debt management rather than daily operational pricing adjustments.
Q: What is the primary goal of this restructuring?
A: The primary objective is to reorganize billions in debt, likely by renegotiating terms with creditors to create a more sustainable capital structure that supports the long-term viability of the rail network.


Related Posts